A Study on Optimal Parameters of Long Short-Term Memory (LSTM) Networks for Cryptocurrency Price Forecasting: A Case Study of Bitcoin, Dogecoin, and Ethereum
DOI:
https://doi.org/10.57260/stc.2026.1110Keywords:
Artificial neural network, Cryptocurrency, Digital currency, Prediction modellingAbstract
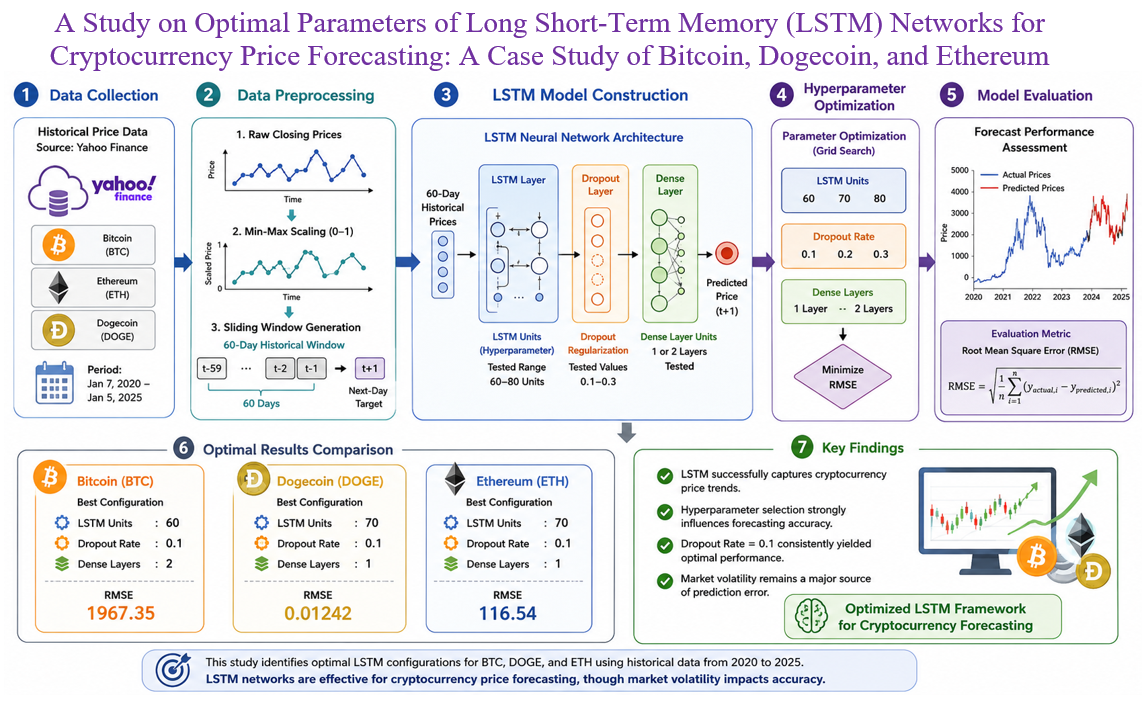
Digital currencies such as Bitcoin (BTC), Ethereum (ETH), and Dogecoin (DOGE) are increasingly popular, emphasizing the importance of price forecasting. This study employs a Long Short-Term Memory (LSTM) artificial neural network to predict digital currency prices. Historical price data were collected from Yahoo Finance, spanning from January 7, 2020 to January 5, 2025. The data were preprocessed using Min-Max Scaling, and a 60-day historical window was used to forecast the next day’s price. Subsequently, an LSTM model was constructed by tuning three parameters including, the number of LSTM units, the Dropout Rate, and the number of Dense Layer units and its performance was evaluated using the root mean square error (RMSE). The experimental results revealed that for BTC, the model with 60 LSTM units, a Dropout Rate of 0.1, and 2 Dense Layer units achieved the lowest RMSE of 1967.35; for DOGE, the model with 70 LSTM units, a Dropout Rate of 0.1, and 1 Dense Layer unit achieved the lowest RMSE of 0.01242; and for ETH, the model with 70 LSTM units, a Dropout Rate of 0.1, and 1 Dense Layer units achieved the lowest RMSE of 116.54. These findings demonstrate that LSTM networks can effectively forecast digital currency price trends, although forecasting accuracy may be impacted by market volatility.
Downloads
References
ณัฐชยา เพียรดี. (2552). การพัฒนาโครงข่ายประสาทเทียมสำหรับพยากรณ์การผลิต. (วิทยานิพนธ์ปริญญามหาบัณฑิต, มหาวิทยาลัยเทคโนโลยีพระจอมเกล้าพระนครเหนือ).
ณัฐพล ฐิตะวีระ. (2563). การศึกษารูปแบบการพยากรณ์ราคาหลักทรัพย์โดยใช้แบบจำลองการเรียนรู้เชิงลึก. (การค้นคว้าอิสระปริญญามหาบัณฑิต, จุฬาลงกรณ์มหาวิทยาลัย).
ธีรภพ แสงศรี, เทวา พรหมนุชานนท์, และ รุจิพันธุ์ โกษารัตน์. (2567). การวิเคราะห์เปรียบเทียบโมเดล ARIMA และ LSTM สำหรับการพยากรณ์ราคาบิตคอยน์: การประยุกต์ใช้เครื่องมือเรียนรู้ของเครื่อง. Journal of Information Science Research and Practice, 12(2), 95-107. https://so03.tci-thaijo.org/index.php/jiskku/article/view/277726
นิติกร จันหาญ. (2564). การพยากรณ์ราคาบิตคอยน์ด้วยเทคนิคการเรียนรู้ของเครื่อง. (วิทยานิพนธ์ปริญญามหาบัณฑิต, มหาวิทยาลัยมหาสารคาม). http://202.28.34.124/dspace/bitstream/123456789/2412/1/62011284507.pdf
ปิยธิดา รุ่งเรือง. (2565). การพยากรณ์ราคาสกุลเงินดิจิทัลและการจัดพอร์ตการลงทุนโดยใช้อนุกรมเวลาฟัซซี่นิวโทรโซฟิกแบบลังเลที่มีค่าเดียวร่วมกับโมเดล LSTM. (วิทยานิพนธ์มหาบัณฑิต, บัณฑิตวิทยาลัย, มหาวิทยาลัยเชียงใหม่).
พชร พงษ์สิทธิศักดิ์. (2563). การศึกษาเปรียบเทียบการพยากรณ์ความผันผวนและราคาหลักทรัพย์ ดัชนี SET50 ระหว่างตัวแบบทางเศรษฐมิติและอัลกอริทึมแอลเอสทีเอ็ม (LSTM). (วิทยานิพนธ์ปริญญามหาบัณฑิต, มหาวิทยาลัยธรรมศาสตร์).
วิศรุต เลิศทวีเดช. (2564). การผสานการวิเคราะห์เชิงเทคนิคและแบบจำลองการเรียนรู้เชิงลึกสำหรับการซื้อขายน้ำมันดิบ. (วิทยานิพนธ์ปริญญามหาบัณฑิต, จุฬาลงกรณ์มหาวิทยาลัย). https://digital.car.chula.ac.th/chulaetd/5398/
อุทิศ พงศ์จิรวัฒนา, อนุพงศ์ สุขประเสริฐ, นันทิมา แพงทรัพย์ และ มะลิวัลย์ สารภาพ. (2566). การพยากรณ์ราคาคริปโทเคอร์เรนซีล่วงหน้าด้วยแบบจำลอง ARIMA. วารสารวิทยาการจัดการ มหาวิทยาลัยราชภัฏอุดรธานี, 5(4), 1–11. https://so08.tci-thaijo.org/index.php/MSJournal/article/view/2343
Cibikdiken, A. O., & Karakoyun, E. S. (2018). Comparison of ARIMA time series model and LSTM deep learning algorithm for Bitcoin price forecasting. In Proceedings of the 13th Multidisciplinary Academic Conference, Prague, Czech Republic.
Goodfellow, I., Bengio, Y., & Courville, A. (2016). Deep Learning. MIT Press.
Hochreiter, S., & Schmidhuber, J. (1997). Long short-term memory. Neural Computation, 9(8), 1735–1780. https://doi.org/10.1162/neco.1997.9.8.1735
Hyndman, R. J., & Koehler, A. B. (2006). Another look at measures of forecast accuracy. International Journal of Forecasting, 22(4), 679–688. https://doi.org/10.1016/j.ijforecast.2006.03.001
Mehtab, S., Sen, J., & Dutta, A. (2020). Stock price prediction using machine learning and LSTM-based deep learning models. https://arxiv.org/pdf/2009.10819
Olah, C. (2015). Understanding LSTMs Networks. Colah's Blog. https://colah.github.io/posts/2015-08-Understanding-LSTMs/
Downloads
Published
How to Cite
Issue
Section
License
Copyright (c) 2026 Science and Technology to Community

This work is licensed under a Creative Commons Attribution-NonCommercial-NoDerivatives 4.0 International License.
1. Articles, information, content, images, etc. that are published in "Science and Technology for Community Journal" is the copyright of science and Technology for Community Journal. Chiang Mai Rajabhat University. If any person or organization wants to distribute all or any part of it or do any action Must have written permission from the science and Technology for Community Journal, Chiang Mai Rajabhat University.
2. Content of articles appearing in the journal is the responsibility of the author of the article. The journal editor is not required to agree or take any responsibility.